
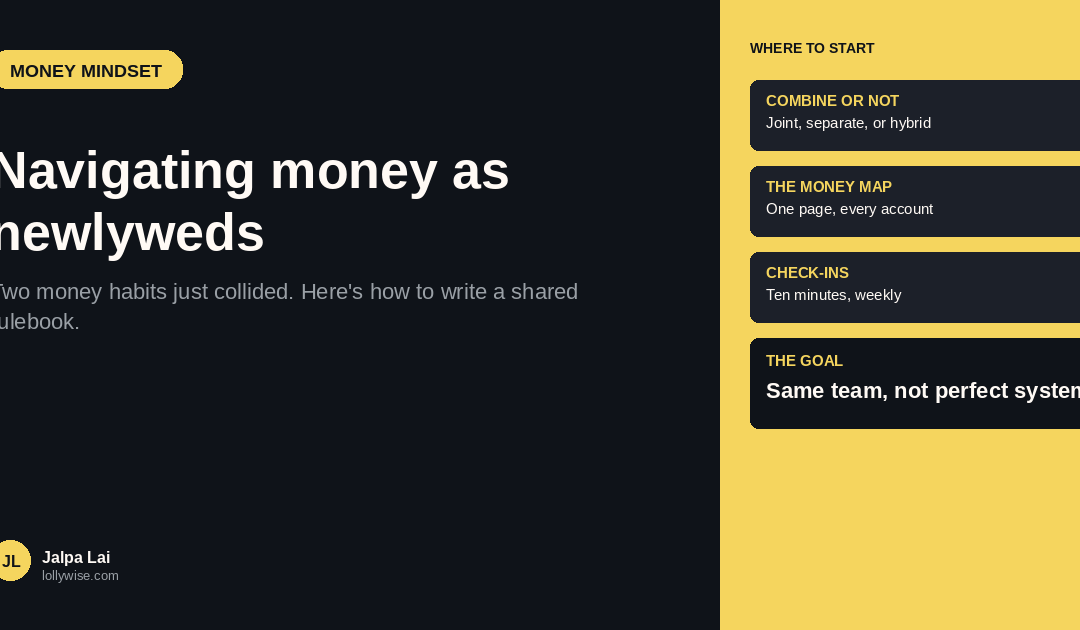
So you’re married, congratulations. Money as newlyweds always feels a little different once the wedding’s over and real life starts asking questions. Somewhere between the thank-you cards and the first proper grocery shop together, money starts showing up in ways it never quite did before: whose account pays the broadband bill, who’s covering date night this week, and that slightly awkward pause when one of you mentions a savings goal the other’s never heard of. None of that means you’re doing it wrong. It just means two separate money habits have collided, and nobody’s handed you a shared rulebook yet.
Here’s the thing: you don’t need a perfect system, you need a shared one. Something that actually fits how the two of you live, not a template borrowed from someone else’s marriage.
How to Combine Money as Newlyweds
Start with the boring decision that saves you a hundred small arguments later: how you’re actually going to combine money. Fully joint, fully separate, or the hybrid most couples land on eventually, a joint account for bills, personal accounts for everything else, doesn’t matter which. What matters is choosing one on purpose, deciding together what “fair” means (50/50, or proportional to what you each earn), and writing it down somewhere you’ll both remember, before life gets busy and the default becomes whoever complains loudest.
Once that’s settled, spend one evening building what’s basically a shared money map: every account, every card, every subscription, every due date, all on one page. It sounds tedious, and it kind of is, but it’s the fastest way to kill the “wait, whose account was paying that?” moment for good, because you’re finally both looking at the same picture instead of guessing at each other’s.
The insurance check most couples skip
While you’re at it, take a look at your insurance too. Between the two of you there’s probably some overlap left over from single life, two car policies where one would do, or a gap neither of you has noticed, especially if one of you would genuinely struggle without the other’s income. You don’t need to overhaul everything, just close the obvious gaps and stop quietly paying twice for the same protection.
Set goals you can actually hit
From there, sit down together and pick two or three goals you both actually care about, an emergency fund, a card you want gone, a house deposit, whatever it is for you two. Use what you actually earned last year, not what you’re hoping for, to ground the plan in reality, and if the numbers feel tight, shrink the goal or stretch the timeline rather than setting yourselves up to fail by month two.
Build a budget you’ll actually keep
Build the budget around all of it: fixed costs first, a realistic limit for groceries and fun, savings automated so it happens without either of you having to remember. Give yourselves a weekly ten-minute check-in, decisions only, not a blame session, and test it for two full pay cycles before deciding anything isn’t working. A lot of money friction is really about communication, not the numbers themselves, so treat those check-ins as the actual habit you’re building.
The small habits that make the biggest difference
A few small habits do more for a relationship’s money than any spreadsheet ever will. A twenty-minute monthly money chat, just balances, bills, anything coming up, keeps decisions joint instead of a surprise. Both of you having access to the accounts that matter, plus a shared, up-to-date list of logins, closes blind spots before they turn into resentment.
An automatic transfer to savings the moment payday lands builds your buffer without either of you having to think about it, and a quick weekly text about one smart money choice you each made keeps things feeling like teamwork rather than a scoreboard. And one simple rule, wait 24 hours before any non-essential spend over an amount you’ve agreed on, quietly kills most impulse buys and gives you a natural moment to check in with each other first.
If money conversations have felt tense before now, our guide on how to stop arguing with your partner about money has more on turning that tension into teamwork.
A lot of money friction isn’t about the numbers. It’s about two people learning to make decisions without stepping on each other’s toes.
The goal was never a perfect system. It was staying on the same team.
FAQ
Do we need to merge everything into one account straight away?
Not necessarily. Plenty of couples start with a joint account just for the shared stuff, rent or mortgage, bills, groceries, joint goals, and keep their own accounts for personal spending. Pick a simple split, then revisit it after a couple of months once you can see what actually feels fair.
What if we earn quite different amounts?
A percentage-based split tends to feel fairer than a straight 50/50 here: you both put in the same percentage of what you earn toward shared costs and goals, keep the rest as your own, and agree on a small no-questions amount each so neither of you feels like you're asking permission to spend your own money.
Pension or ISA, where should extra money go?
Honestly, most people end up using both. A pension gets a boost from tax relief, often with an employer top-up too, but the money's locked away until retirement age. An ISA gives you more flexibility, no tax on what you earn inside it, and you can get at it sooner if you genuinely need to.
Can we invest together even if we keep some accounts separate?
Yes, and it's often the simplest way to work toward a shared goal like a house deposit or future travel. A joint stocks and shares ISA built around one goal and one monthly amount is an easy place to start.
Guest post by Christopher Haymon
Jalpa Lai - Lollywise
Jalpa is a financial and life coach for young adults aged 18-30, based in Surrey. She founded Lollywise, winner of Life Coaching Service of the Year for South of England at the Prestige Awards 2025/26.